FREE GUIDE | PROPERTY PROTECTION
Protect your property's equity, without moving it out of your name
Our guide to second mortgage property protection, in plain English.
Free in our community. No credit card, no sales calls. Reading time on this page: about 4 minutes.
Why Property Needs Protecting
If your property is in your own name, it's exposed. Business owners, directors, landlords and professionals can all be sued
personally, and insurance doesn't always pay.
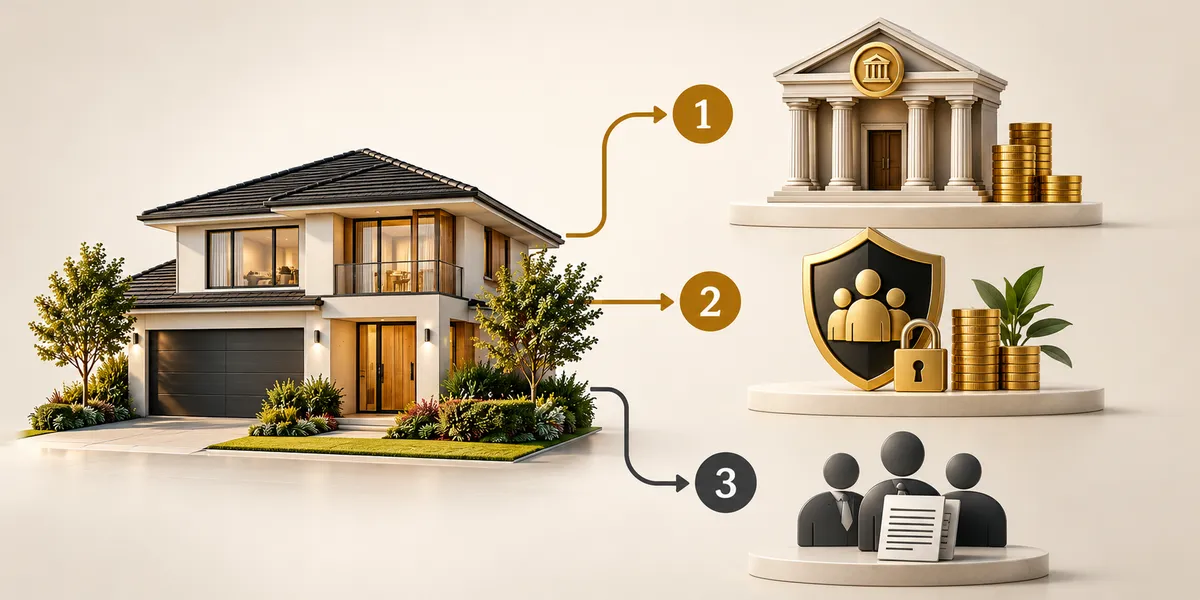
Three Ways to Protect a Property
Option
Upside
Downside
Buy in a trust from the start
Protected from day one
Can lose the main residence exemption and make negative gearing harder; extra land tax in some states
Transfer into a trust
Protects a property you already own
Stamp duty, possible capital gains tax and extra land tax: often very expensive
Second mortgage
Stays in your name: no stamp duty, no capital gains tax on transfer, no extra land tax
Upfront set-up cost, about $20,000 for one property
How a Second Mortgage Works
A loan and the security for it are two different things. A registered mortgage is security: when a property is sold, mortgage holders are paid before ordinary creditors.
With a second mortgage strategy, a finance trust set up for your family takes a registered mortgage over your property, behind the bank. If the property is ever sold, the bank is paid first, then your family's trust, then everyone else.
Example. Sam's home is worth $2 million, with a $500,000 bank loan. Without protection, $1.5 million of equity is exposed. With a second mortgage to Sam's family finance trust, that equity is paid to the trust before other creditors.
The Steps
Strategy meeting to confirm it suits you.
Lawyers set up the finance trust and documents.
The lawyer plans and supervises the transfer of funds (they may be unavailable for around five weeks).
The loan agreement is signed and the mortgage registered.
A final meeting to go through everything.
Important: it must be set up before any problem. Transactions made to avoid existing creditors can be reversed.
Get the Full Brochure
Want the full guide?
The full brochure goes deeper, with more examples and answers to common questions. It's free in our community, along with our free training videos, podcasts and news.
Inside the full brochure:
the three ways to protect a property, compared
how mortgages and priority work, with examples
different scenarios: with a bank loan, without one, and buying new
common questions about selling, bank loans and tax
Where to Next
Watch the free training: our Free Training Centre has videos on second mortgages. Join free to watch. Join Free Community
Read the service page: Second Mortgage Property Protection
Get it set up: Second Mortgage Set Up
Not sure? Standard Consultation
Frequently Asked Questions
Does it affect getting a bank loan?
Sometimes it adds a little paperwork, and occasionally a bank won't accept it.
What happens when I sell?
Settlement happens as normal: the bank is paid, then your finance trust.
Does it save tax?
No. It's about protection only.
Protect the equity you've worked for
Download the full guide free, or book a call to see if it suits you.
Know how it works. Keep more of your hard-earned wealth. Leave a legacy.
Education and strategy for Australians who want to protect what they've built. Online, by Zoom.
Email: [email protected]
Free wealth protection training videos.
No credit card. No sales calls.
START HERE
ABOUT
FOLLOW
Important information. Global Wealth Club provides general education and information only. We are not licensed financial advisers, lawyers or accountants, and nothing on this website is financial, legal, tax or accounting advice. Warren has qualifications in law, accounting and financial planning, and we work closely with licensed professionals as the specialists. Our role is to educate you, help you design your overall strategy, and be the bridge to those specialists. Always get advice from a licensed financial adviser, lawyer or accountant about whether a strategy is right for you. We don't sell financial products or take commissions. Read our full Disclaimer.
© 2026 Global Wealth Club. Founded 2019.